Education Loan vs Scholarship vs Assistantship for Study Abroad 2026: The Smartest Funding Mix for Indian Students
Education Loan vs Scholarship vs Assistantship for Study Abroad 2026: The Smartest Funding Mix for Indian Students
 scholarabroad
Why Your Funding Strategy Matters More Than Ever in 2026
Studying abroad in 2026 is exciting, but it comes with a serious price tag. For Indian students, the total cost of attendance at top universities in the US, UK, Canada, Australia, or Europe often ranges from ₹25 lakh to over ₹80 lakh for a two-year master’s program. Tuition alone can consume a large portion of that, and living expenses in cities like New York, London, or Toronto add significantly more.
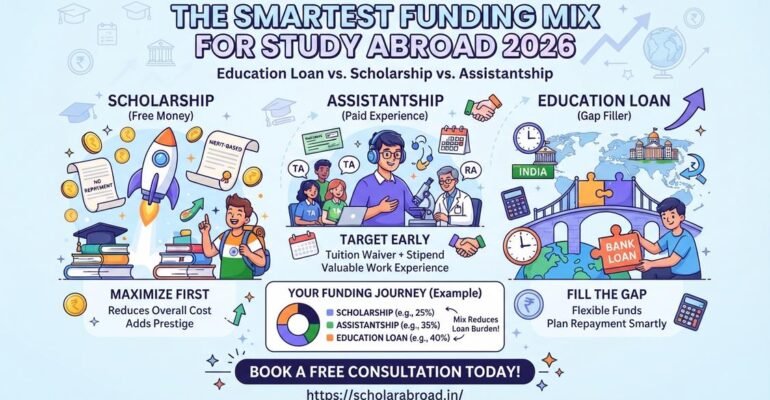
This is why the old approach of “just take a loan” or “hope for a scholarship” no longer works. The smartest students are building a funding mix — combining education loans, scholarships, and assistantships to reduce risk, lower interest outgo, and improve their chances of a smooth financial journey. This guide breaks down each option and shows you how to combine them effectively.
Estimated reading time: 10 minutes
Key Takeaways
- Sequence your funding: Prioritize scholarships and assistantships (free money) first, then use loans to fill the remaining gap.
- Assistantships are powerful: A TA or RA can include a tuition waiver plus a monthly stipend, dramatically cutting your total cost.
- Loans are flexible, not free: Use education loans strategically and compare interest rates, moratorium periods, and prepayment charges.
- A smart funding mix reduces risk: It lowers interest outgo, eases financial stress, and can improve your visa approval chances.
- Start early: Begin planning 12–18 months before your intake to maximize scholarships and assistantship opportunities.
Table of Contents
- Why Your Funding Strategy Matters More Than Ever in 2026
- Key Takeaways
- Education Loan vs Scholarship vs Assistantship: What’s the Difference?
- Scholarship vs Assistantship vs Loan Comparison: Which Should You Prioritize?
- How to Build the Smartest Funding Mix for Studying Abroad
- Mixing Loan and Scholarship for Study Abroad: A Real Example
- Key Takeaways for 2026
- How Scholar Abroad Can Help You Build Your Funding Mix
Education Loan vs Scholarship vs Assistantship: What’s the Difference?
Before you decide on a funding mix, you need to understand what each option really is and how it works.
Education Loan
An education loan is borrowed money that you repay with interest. In India, banks and NBFCs offer specialized overseas education loans, often covering tuition, living expenses, travel, and even insurance. Many loans are secured against collateral, but unsecured loans are also available for select universities and programs.
Pros: You can fund almost any program, repayment starts after a moratorium period, and interest paid may qualify for tax benefits under Section 80E in India.
Cons: You graduate with debt, interest accrues during the study period (unless you service it), and currency fluctuation can increase your repayment burden.
Scholarship
A scholarship is free money awarded based on merit, need, diversity, or specific talents. Scholarships can be partial (covering 10–50% of tuition) or full (covering tuition, fees, and sometimes living costs). They do not need to be repaid.
Pros: Reduces your overall cost and loan burden, adds prestige to your profile, and may open doors to other opportunities.
Cons: Highly competitive, deadlines are strict, and many scholarships only cover a portion of expenses.
Assistantship (Teaching or Research)
An assistantship is a paid position at the university, usually for graduate students. In the US and Canada, teaching assistantships (TA) and research assistantships (RA) are common. They often come with a tuition waiver plus a monthly stipend. In return, you work 10–20 hours per week teaching, grading, or conducting research.
Pros: Significant financial support, valuable work experience, strong faculty connections, and often a pathway to a job or PhD.
Cons: Competitive, usually requires strong academic or research credentials, and may extend your time to graduation if not managed well.
Scholarship vs Assistantship vs Loan Comparison: Which Should You Prioritize?
The best approach is not to choose one over the other, but to sequence them strategically.
Step 1: Maximize Scholarships and Grants First
These are free funds. Start by researching university-specific scholarships, government schemes (like the National Overseas Scholarship or Fulbright-Nehru), and private foundations. Even a 20% tuition scholarship can save you ₹5–10 lakh over two years.
Step 2: Target Assistantships for Tuition Waivers and Stipends
If you are applying for a research-oriented master’s or PhD, assistantships can be more valuable than small scholarships. A teaching assistantship funding abroad explained simply: you teach undergraduate classes, and in exchange, you get a tuition waiver and a stipend that covers living costs. Research assistantships for international students abroad work similarly, but you assist a professor’s research project.
Step 3: Use Education Loans to Fill the Gap
After scholarships and assistantships, you may still have a funding gap. This is where an education loan for overseas education in India 2026 becomes essential. A loan can cover the remaining tuition, living expenses, and even a buffer for emergencies.
How to Build the Smartest Funding Mix for Studying Abroad
Here is a practical framework for Indian students in 2026.
1. Estimate Your Total Cost of Attendance
Include tuition, fees, health insurance, rent, food, books, travel, and a 5–10% buffer for currency fluctuations. For example, a two-year MS in the US may cost $60,000–$100,000 (₹50–85 lakh).
2. Apply for Scholarships Aggressively
Create a spreadsheet of at least 10–15 scholarships. Track deadlines, essay requirements, and eligibility. Even small awards add up.
3. Pursue Assistantships Early
Contact professors whose research aligns with your interests before you apply. Mention your interest in an RA or TA position. For teaching assistantships, highlight any teaching, tutoring, or mentoring experience.
4. Secure an Education Loan for the Remaining Amount
Compare lenders on interest rates, processing fees, moratorium period, and prepayment charges. A secured loan against property or fixed deposit usually offers lower interest rates than an unsecured loan.
5. Plan Your Repayment Strategy
If you have a loan, start paying simple interest during the moratorium if possible. This reduces your total interest outgo significantly. Also, consider working part-time on campus (up to 20 hours per week in the US) to cover personal expenses.
Mixing Loan and Scholarship for Study Abroad: A Real Example
Priya, an Indian student, got admitted to a top US university for an MS in Data Science. Total cost: $80,000. She received a $20,000 merit scholarship and a teaching assistantship that covered 50% of tuition plus a $1,200 monthly stipend. She took an education loan of $30,000 to cover the remaining tuition and living expenses. By mixing all three, she reduced her loan burden by more than half compared to taking a full loan.
Key Takeaways for 2026
- Scholarships and assistantships are free or partially free money — prioritize them.
- Education loans are flexible but come with interest — use them to fill gaps, not as a first resort.
- A funding mix reduces financial stress and improves your chances of visa approval.
- Start planning 12–18 months before your intake.
How Scholar Abroad Can Help You Build Your Funding Mix
At Scholar Abroad, we specialize in helping Indian students navigate the complex world of study abroad funding. Our experts guide you through scholarship applications, assistantship opportunities, and education loan comparisons. We help you create a personalized funding strategy that matches your academic profile, financial situation, and career goals.
Whether you need help finding the right scholarship, crafting a winning assistantship application, or securing a low-interest education loan, Scholar Abroad is your trusted partner. Book a free consultation today and take the first step toward a financially smart study abroad journey in 2026.